
Mortgage Broker for Sutherland, Kirrawee & Surrounds
Whether you’re buying your first apartment near Sutherland station, upgrading to a family home in Kareela or Jannali, or eyeing a bush or water outlook in Bonnet Bay, Oyster Bay or Como, Ingram Financial is a local mortgage broker in Sutherland who knows these suburbs well. We compare loans from dozens of lenders and handle the process for you, from first chat to settlement.
Suburbs covered: Sutherland, Kirrawee, Jannali, Kareela, Bonnet Bay, Oyster Bay and Como.
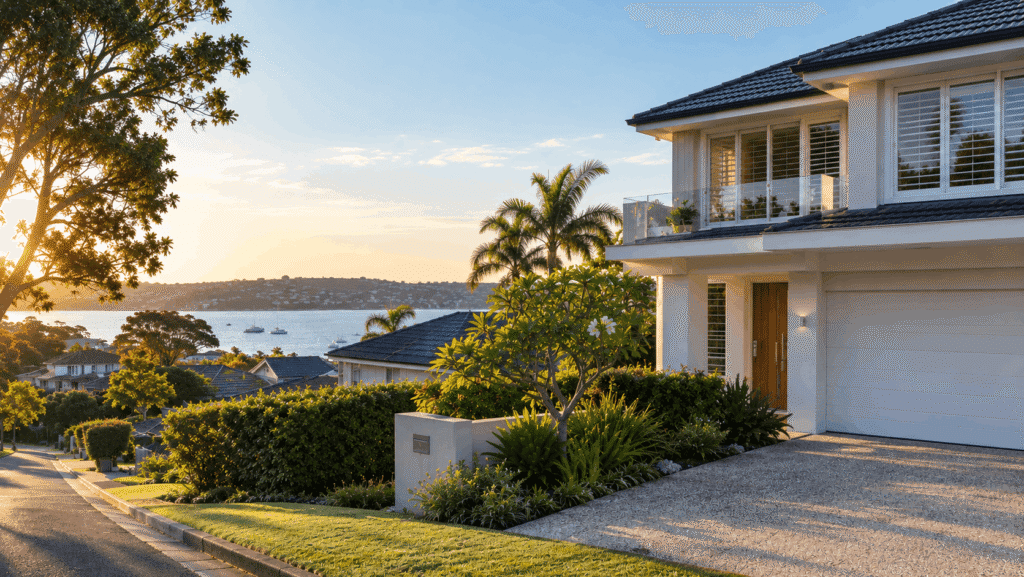
Buying in Sutherland, Kirrawee and the Bays
Within a few kilometres you’ll find high-rise units beside the station, family streets in Jannali and Kareela, and bush-backed homes in Bonnet Bay and Oyster Bay. Each kind of property raises different questions for a lender.
Sutherland Is Mostly Units: What That Means for Your Loan
At the 2021 Census, two in three occupied homes in Sutherland (66.7%) were flats or apartments, against 21.7% across NSW, and 42.4% of households were renting. Next door in Kirrawee the mix is closer to even: 49.5% houses, 15.2% townhouses and 34.7% apartments. That matters for your loan. When a building or postcode has a lot of similar units, some lenders ask for a bigger deposit, cap the loan or exclude very small units. We check each lender’s apartment rules for the specific building before you make an offer, so the valuation doesn’t catch you out.
The Sutherland-Kirrawee Planning Proposal and Buying Off the Plan
Council’s Sutherland-Kirrawee Planning Proposal (PP-2026-712) is at the NSW Gateway Determination stage, which began on 1 April 2026. It aims to increase height and density around the Sutherland centre so the area can meet a state target of 6,000 new homes by 2029. If it goes ahead, expect more off-the-plan apartments near both stations. Off-the-plan loans are approved on today’s valuation but settle on a new valuation when the building is finished. If that figure comes in low, you cover the gap. We’ll help you plan a buffer and choose a lender whose off-the-plan rules suit.
Dual Occupancy and Terraces Near Sutherland and Kirrawee Stations
Since 28 February 2025, the NSW Low and Mid-Rise Housing Policy has applied within 800 metres’ walk of Sutherland station and town centre and Kirrawee station and town centre. In those areas, a dual occupancy on R2 land needs at least 450 m² and a 12 m frontage, and terraces or townhouses can be built on R2 lots of 600 m² or more. Jannali and Como stations are not on the list, and the policy doesn’t apply to bushfire-prone land. If you’re buying for the development potential, we’ll look at construction finance before you exchange, because lenders value the site as it stands today. We work with lenders who fund dual occupancy and duplex builds.
Moving Up in Jannali, Kareela and Como
Jannali and Como sit on the Illawarra line and Kareela is tucked in between, so these streets suit families stepping up from a unit. The hard part is usually timing. Buy first and the lender needs to be satisfied you can carry both loans until your sale settles, often through a bridging loan sized on your expected end debt. Sell first and your budget is certain, but you may need to rent or negotiate a long settlement. We’ll set out the numbers for both so you can decide with your eyes open.
Overland Flow Flooding in Bonnet Bay, Oyster Bay and Como
Sutherland Shire Council exhibited its revised Overland Flow Flood Study from July to September 2026. Once it is adopted, homes inside the mapped flood planning area may get a new notation on their section 10.7 planning certificate. Council says the notation doesn’t stop development but can bring extra planning controls. Overland flow is often treated differently from riverine flooding in home insurance, and lenders need building insurance in place at settlement. If you’re buying near the Woronora or Georges rivers, read the planning certificate in the contract and get an insurance quote before you exchange. Streets that back onto bushland are worth checking on the bushfire-prone land map at the same time.
How a Sutherland Mortgage Broker Can Help
- Off-the-plan and apartment loans: matching the building to a lender whose unit size and density rules fit, and planning for the valuation at settlement
- Construction loans for dual occupancies and terraces near Sutherland and Kirrawee stations, and for knockdown-rebuilds
- First home loans for a first unit near the station, using the First Home Guarantee and NSW first home buyer stamp duty concessions where you’re eligible
- Upgrading from a Sutherland unit to a house in Jannali, Kareela or Como
- Investment loans for apartments and townhouses within walking distance of the train
Prefer to talk face to face? We can meet at your home or a café near you, or catch up by phone or video.
Tips for Buyers in Sutherland & Kirrawee
- Have pre-approval in hand before an auction. A winning bid is binding on the day with no cooling-off period, so line up your finance first. Our pre-approval guide explains the process, and a pre-approval usually lasts about three months.
- Ask for the strata records on any unit. Look at the capital works fund balance, recent special levies and any defect reports, because the valuer and the lender will weigh them too.
- Read the sunset clause in an off-the-plan contract. It sets how long the developer has to finish the building, which may be well beyond the life of any pre-approval.
- Test your borrowing power with more than one lender. Our borrowing power calculator gives you a rough figure, and we can show you how particular lenders would assess you.
Local FAQs
Possibly. Eligible first home buyers may be able to buy with a 5% deposit through the First Home Guarantee without paying lenders mortgage insurance, but lenders also have their own rules for small or high-density units. We’ll check both the scheme’s eligibility and the lender’s apartment policy for the specific property.
Possibly. Dual occupancies have been permitted with consent in R2 zones across NSW since July 2024, but the more generous Low and Mid-Rise standards apply only within 800 metres of the listed centres, such as Sutherland and Kirrawee, and not to bushfire-prone land. Check the zoning and planning certificate first, then talk to us about construction finance before you commit to plans.
Not on its own. Lenders need building insurance in place at settlement and a valuation they’re comfortable with. A flood notation can push up premiums or influence the valuer, so get an insurance quote before you exchange and let us know what the certificate says.
Ready to talk to a local mortgage broker in Sutherland? Book a free chat or call 0402 283 480.
Looking for another part of the Shire? We also help buyers in Miranda & Caringbah, Cronulla & Kurnell, Menai, Bangor and Engadine & Heathcote, or see all the areas we cover in the Sutherland Shire.
The information on this page is general in nature and does not take into account your objectives, financial situation or needs. Eligibility criteria apply to government schemes. Lending criteria, fees and charges apply. Speak to us for advice specific to your situation.
Need Some Help?
Not sure where to start? That’s exactly what we’re here for. Drop us a message and we will get back to you within one business day with clear, honest advice tailored to your situation.