
Mortgage Broker for Engadine & Heathcote
Surrounded by national park and connected by the Illawarra line, Engadine, Heathcote, Loftus and Yarrawarrah offer a relaxed bushland lifestyle while staying within reach of the city. Ingram Financial is a local mortgage broker in Engadine and the surrounding suburbs, comparing loans from dozens of lenders for first home buyers, families and builders.
Suburbs covered: Engadine, Heathcote, Loftus and Yarrawarrah.
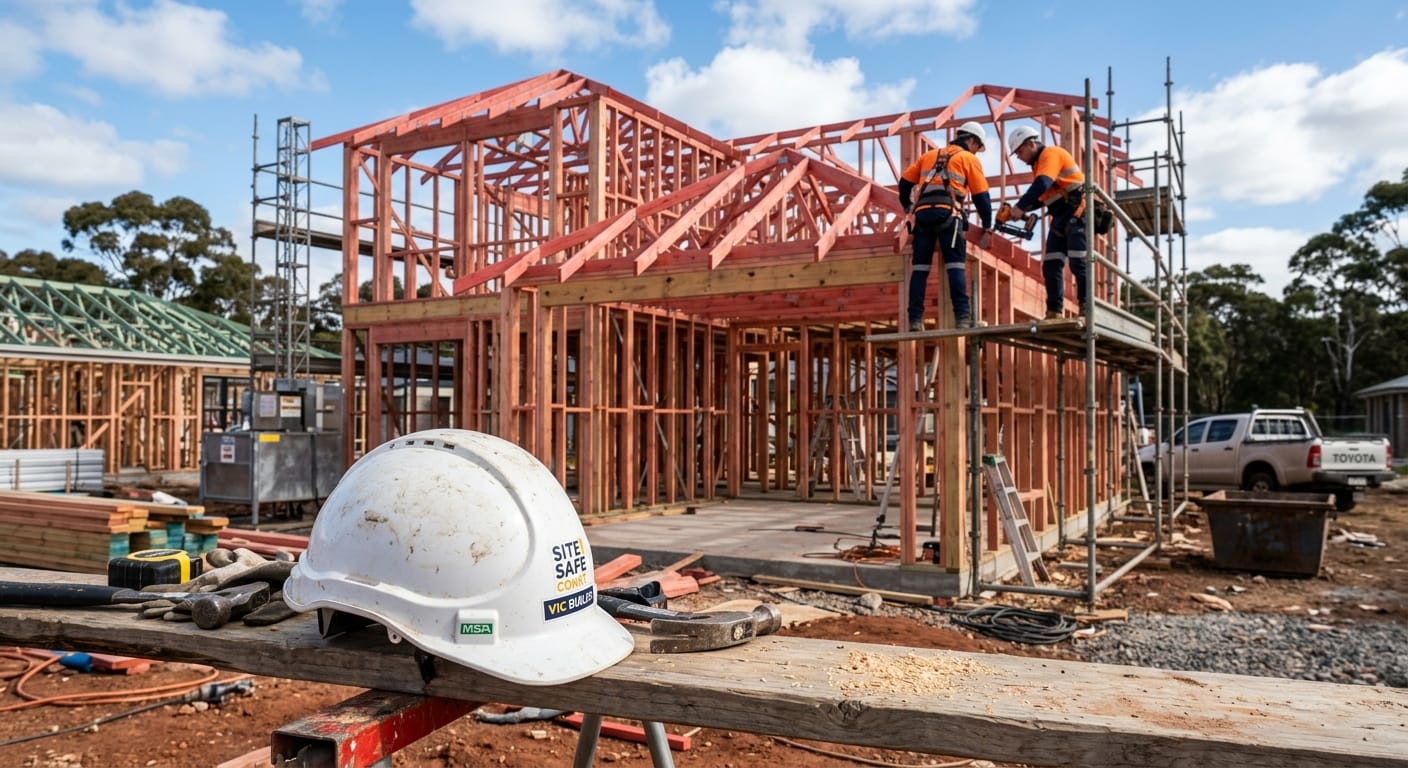
Buying in Engadine, Heathcote, Loftus and Yarrawarrah
Engadine and Heathcote by the Numbers
Engadine and Heathcote are owner-occupier suburbs. At the 2021 Census, 79.4% of homes in Engadine and 74.3% in Heathcote were separate houses, and only 13.5% and 11.3% of households were renting, well below the NSW figure of 32.6%. Just 12.7% of homes in each suburb were apartments. First home buyers here are often competing for a small pool of units and townhouses, or stretching to a house. We’ll check your First Home Guarantee and stamp duty eligibility first, so you know your real ceiling before you start bidding.
The First Home Buyer Thresholds That Matter Here
Two numbers matter for first home buyers in the upper Shire. In NSW, first home buyers pay no transfer duty on homes up to $800,000 and a reduced rate up to $1,000,000 (thresholds in place since 1 July 2023). Separately, the federal 5% Deposit Scheme (First Home Guarantee) lets eligible buyers purchase with a 5% deposit and no lenders mortgage insurance, up to a $1.5 million price cap in Sydney, with no income cap since 1 October 2025. We’ll show you where a property sits against both thresholds before you make an offer.
Engadine Town Centre and the Low and Mid-Rise Rules
Engadine town centre is the only upper-Shire location named in the NSW Low and Mid-Rise Housing Policy. Heathcote, Loftus and Yarrawarrah stations are not included. Within 800 metres’ walk of the centre, R2 lots of 450 m² or more with a 12 m frontage can qualify for dual occupancy, unless the land is bushfire-prone. If you’re thinking of building a duplex to live in one half and rent or sell the other, we’ll compare construction lenders and check how each one treats the finished properties.
Checking Bushfire-Prone Land Before You Borrow
Much of Engadine, Heathcote, Loftus and Yarrawarrah borders Royal National Park and Heathcote National Park. Bush fire prone land maps are certified by the NSW RFS Commissioner, and you can check any address with the RFS online tool or the NSW Planning Portal. The result also appears on the section 10.7 planning certificate in the sale contract. New homes and many renovations must meet Planning for Bush Fire Protection, which the RFS is currently reviewing. Check early, get a BAL assessment if you’re building, and we’ll make sure your loan covers the real cost.
How an Engadine Mortgage Broker Can Help
- First home loans: we check where a property sits against the NSW duty thresholds and the First Home Guarantee cap before you bid
- Construction loans for new homes, duplexes and granny flats on upper-Shire blocks, with BAL costs built into the budget
- Pre-approval so you can move quickly when one of the area’s few units or townhouses comes up
- Upgrading to a bigger home as your family grows
- Refinancing once your first home has built up some equity
We can sit down with you at home or over coffee at a nearby café, or talk it through by phone or video.
Tips for Buyers in Engadine & Heathcote
- Get pre-approved early. First home buyers often compete for the same properties, and pre-approval lets you act quickly. See our pre-approval guide.
- Set your ceiling from the thresholds, not the asking price. Work out the most you can pay while staying under the duty and guarantee limits that apply to you, and stick to it on auction day.
- Building? Sign a fixed-price contract before you finalise the construction loan, because lenders assess the build cost written into that contract.
- Save your genuine savings. Many lenders want to see a history of regular saving, even if you have a gift or a grant towards your deposit.
Local FAQs
Not if you’re an eligible first home buyer and the price is $800,000 or less. Between $800,000 and $1,000,000 you pay a reduced amount, and above $1,000,000 full duty applies. The First Home Guarantee is separate: it could let you buy with a 5% deposit and no lenders mortgage insurance up to $1.5 million. We’ll check both before you make an offer.
It doesn’t usually stop you getting a loan, but it can affect building costs, insurance premiums and some lenders’ appetite for the property. We’ll help you understand the lending side early, and your conveyancer and insurer can advise on the rest.
No. Engadine town centre is the only upper-Shire location in the policy. Under the standard NSW rules, a dual occupancy can still be approved on R2 land with council consent, subject to local controls and bushfire requirements, so check the planning certificate before you draw up plans.
Ready to talk to a local mortgage broker in Engadine? Book a free chat or call 0402 283 480.
Looking for another part of the Shire? We also help buyers in Sutherland & Kirrawee, Miranda & Caringbah, Cronulla & Kurnell, Menai and Bangor, or see all the areas we cover in the Sutherland Shire.
The information on this page is general in nature and does not take into account your objectives, financial situation or needs. Eligibility criteria apply to government schemes. Lending criteria, fees and charges apply. Speak to us for advice specific to your situation.
Need Some Help?
Not sure where to start? That’s exactly what we’re here for. Drop us a message and we will get back to you within one business day with clear, honest advice tailored to your situation.