
This lump sum repayment calculator helps you calculate the savings benefits of making additional lump sum repayments on your home loan.
How Much Could You Save?
Good mortgage management can help you save both time and money on your home loan. Additional lump sum repayments can significantly reduce the amount of interest you pay on your home loan and the term of your loan.
This calculator estimates the time and money you will save on your loan under various lump sum scenarios. Not all home loans allow for lump sum repayments to be made. We have access to dozens of lenders. Get in touch and we can advise on your loan options.
How to use it: click Launch Calculator below, enter your details to see your estimate, then change the figures to compare different scenarios.

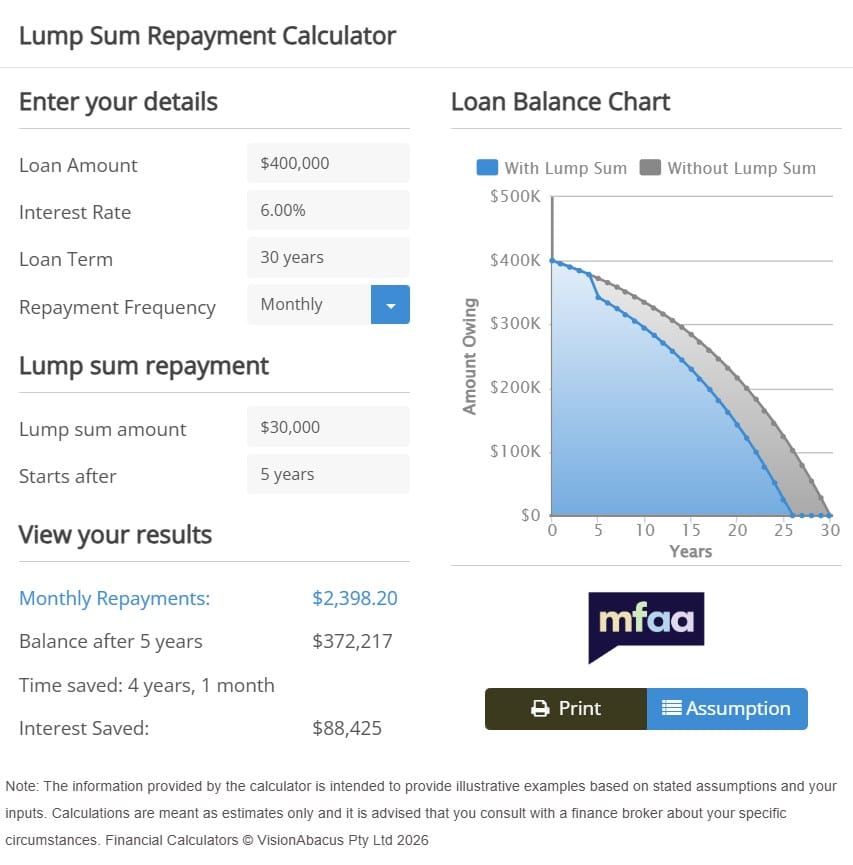
Lump Sum Repayment Calculator
Easily see the impact a lump sum repayment will have on your remaining loan term
How to Use the Lump Sum Repayment Calculator
Enter your current loan balance, interest rate, remaining term and regular repayment. Then add the lump sum amount and when you expect to pay it. The lump sum repayment calculator compares your loan with and without the extra payment and shows:
- how much interest you could save
- how much sooner the loan could be paid off
- your estimated new payoff timeframe
Try a few amounts and timings. An earlier payment usually saves more, because the balance falls sooner.
Lump Sums vs Regular Extra Repayments vs an Offset Account
There are three common ways to put spare money against a home loan. Each one can reduce interest, but they differ in flexibility.
- Lump sum repayment: a one-off amount, such as a tax refund, bonus or inheritance, paid straight off the loan. If your loan has a redraw facility, you may be able to access it later, although redraw rules vary.
- Regular extra repayments: a small amount added to every repayment. Over time, it can save more than a single lump sum.
- Offset account: savings in a linked account reduce the balance that interest is charged on. The money stays accessible to you.
Our guide to offset vs redraw explains the differences in more detail, and Moneysmart has a clear overview of mortgage offset accounts.
Fixed-Rate Loans, Restrictions and Break Costs
Before you make a lump sum payment, check your loan type. Many fixed-rate loans cap extra repayments during the fixed period, and paying more than the allowed amount can trigger break costs. Break costs are charges a lender may apply to cover its loss when a fixed loan is repaid early. They vary with how rates have moved since you fixed.
Variable loans generally allow extra repayments without a penalty. Even so, check your loan contract before you send a large payment.
Worked Example: $20,000 Three Ways
For illustration only, not a current rate. Take a hypothetical $500,000 loan over 30 years at 6.50% p.a., with repayments of about $3,160 a month and no fees.
- A $20,000 lump sum paid after five years could save around $73,500 in interest and take about two years and five months off the loan.
- Keeping the same $20,000 in an offset account from year five, and never touching it, gives a similar interest saving, while the money stays available to you.
- Paying an extra $200 a month from the start could save around $118,000 in interest and about four years and eight months.
These results assume the rate never changes, so test your own numbers in the lump sum repayment calculator.
What the Calculator Cannot Tell You
The calculator assumes a steady rate and repayment, so real results will differ. It also cannot tell you whether putting spare cash into the loan is the right choice for you. For example, you may need an emergency buffer first, or you may have higher-interest debts such as credit cards to clear. Moneysmart covers these trade-offs in its guide to paying off your mortgage faster.
Related Calculators and Guides
Ingram Financial is a mortgage and finance broker based in Bangor, NSW. We help borrowers across the Sutherland Shire, and we also work with clients right around Australia by phone and video.
Lump Sum Repayment Calculator FAQs
Many variable loans allow it. However, some fixed loans limit extra repayments or charge break costs, so check your loan terms or ask us to review them.
It depends on your lender. Some keep your repayment the same so the loan finishes sooner, while others may let you recalculate a lower repayment.
If the money stays untouched, the interest saving can be similar. An offset gives you easier access to the funds, while a lump sum can remove the temptation to spend. Our offset vs redraw guide compares both.
Get Help With Your Loan Strategy
Not sure which option suits you best? Book a free chat and we can run the numbers together.
The information on this page is general in nature and does not take into account your objectives, financial situation or needs. Lending criteria, fees and charges apply. Consider whether it is appropriate for you and speak to us for advice specific to your situation.
Need Some Help?
Not sure where to start? That’s exactly what we’re here for. Drop us a message and we will get back to you within one business day with clear, honest advice tailored to your situation.