
If you’re a doctor, specialist or dentist, home loans for medical professionals can offer benefits that most borrowers can’t access, such as a waiver of lenders mortgage insurance (LMI). Because lenders see many medical careers as secure and well paid, some offer special policies for eligible professionals. However, the rules differ from lender to lender, so it pays to compare.
What Are Some Potential Benefits for Healthcare Professionals?
Some lenders offer home loans for medical professionals with benefits such as:
- Waived lenders mortgage insurance (LMI) for eligible professionals buying with a deposit under 20%, up to limits set by each lender.
- Discounted interest rates with some lenders.
- Waived or reduced fees.
- Streamlined application process.
Which Medical Professionals Are Eligible for Potential Benefits on Their Loans?
Eligible occupations vary by lender and change over time. Doctors, specialists and dentists are the groups most often accepted for professional LMI waivers. Some lenders also include certain other health professionals, while many don’t. In most cases you’ll need current registration with Ahpra (or the relevant board), and some lenders also set a minimum income or ask for membership of a professional body. If you work in healthcare, ask us to check your eligibility against current lender policies.
Occupations Some Lenders May Consider
- Anaesthesiologists/anaesthetists
- Cardiologists
- Chiropractors
- Cosmetic surgeons
- Dental surgeons
- Dentists
- Dermatologists
- Doctors, Intern Doctors, & General Practitioners
- Endocrinologists
- Epidemiologists
- Gastroenterologists
- Gynaecologists
- Immunologists
- Medical registrars
- Medical residents
- Neurologists
- Nurses
- Obstetricians
- Oncologists
- Ophthalmologists
- Optometrists
- Orthodontists
- Paediatricians
- Pathologists
- Pharmacists
- Physiotherapists
- Plastic Surgeons
- Radiologists
- Rheumatologists
- Surgeons
- Urologists
- Veterinary Practitioners
Why Would Lenders Waive LMI for Healthcare Professionals?
LMI is usually charged when you borrow more than 80% of the property’s value. It protects the lender, not you, if the loan defaults. On a large loan it can cost the borrower tens of thousands of dollars.
Some lenders consider eligible medical professionals lower risk, so they may accept a smaller deposit without charging LMI. The maximum loan size and deposit level differ between lenders and professions. As always, the lender still has to be satisfied that you can repay the loan.
Nurses, Midwives and Other Health Workers
Some lenders include nurses in their professional LMI waivers, while others don’t, so the lender you choose matters. Midwives and other health workers should check their eligibility with us. There are also other ways to buy with a small deposit. For example, the Australian Government’s 5% Deposit Scheme lets eligible buyers purchase with a smaller deposit and no LMI. In addition, some lenders offer LMI discounts or lower-deposit options for a wider range of health workers. We can compare these options for you.
Interns, Residents and Registrars
Junior doctors often move between hospitals on fixed-term contracts, which can worry some lenders. However, many lenders understand medical training pathways. They may accept a current contract, or a signed contract for your next rotation, as evidence of ongoing income. As a result, a registrar may be able to use home loans for medical professionals well before becoming a consultant.
It helps to have your contract, recent payslips and registration ready. If you are about to start a new role or change hospitals, speak to us before you resign or sign, because timing can affect how lenders view your income.
How Lenders Treat Different Types of Medical Income
Medical income comes in many forms, and each lender treats it a little differently. In general terms:
- Salary: base PAYG salary is the simplest income to verify.
- Overtime, on-call and allowances: many lenders accept some or all of it, especially with a history, although some shade it.
- Private practice: lenders usually assess it from your tax returns, so timing of lodgement matters.
- ABN and locum work: contractors are usually assessed like self-employed borrowers, although some lenders accept a shorter trading history for professionals.
- Trusts, companies and service entities: income paid through a structure needs the entity’s financials as well as your own.
For more detail, read how lenders calculate your income and our self-employed loans page.
What Documentation Do I Need to Provide?
Lenders will generally ask for you to submit two or three recent payslips and an employment summary. If you work for yourself, you will usually need your latest personal tax return, ATO notice of assessment and either 12 months of BAS or a second year’s tax return. Your registration details and, for new roles, your employment contract help too.
Buying a Practice or Fitting Out Rooms
Medical lending isn’t only about your home. Many clinicians also need finance to buy into a practice, purchase goodwill, fit out consulting rooms or buy equipment. Lenders typically look at the practice’s financial history, your experience and the security on offer. We can help with business loans for practice purchases, asset finance for equipment, and commercial loans for buying your own rooms.
Working at Sutherland Hospital or Elsewhere in the Shire?
Many doctors, specialists and dentists live near where they work. If you’re at Sutherland Hospital in Caringbah or a local practice, suburbs like Miranda, Caringbah and Cronulla keep your commute short. Our Miranda and Caringbah mortgage broker page covers that part of the Shire, and our Sutherland Shire mortgage broker page covers the rest.
We’re based in Bangor, NSW. However, we also arrange home loans for medical professionals right across Australia by phone and video, so rosters and night shifts don’t have to get in the way.
Final Considerations
Lenders vary widely in the home loans they offer medical professionals. The amount one lender is willing to offer can be hundreds of thousands of dollars different to another. You will also find differences in interest rates, fees, processing times and features. That is why it is a good idea to shop around to find the right one, or have your broker do it for you.
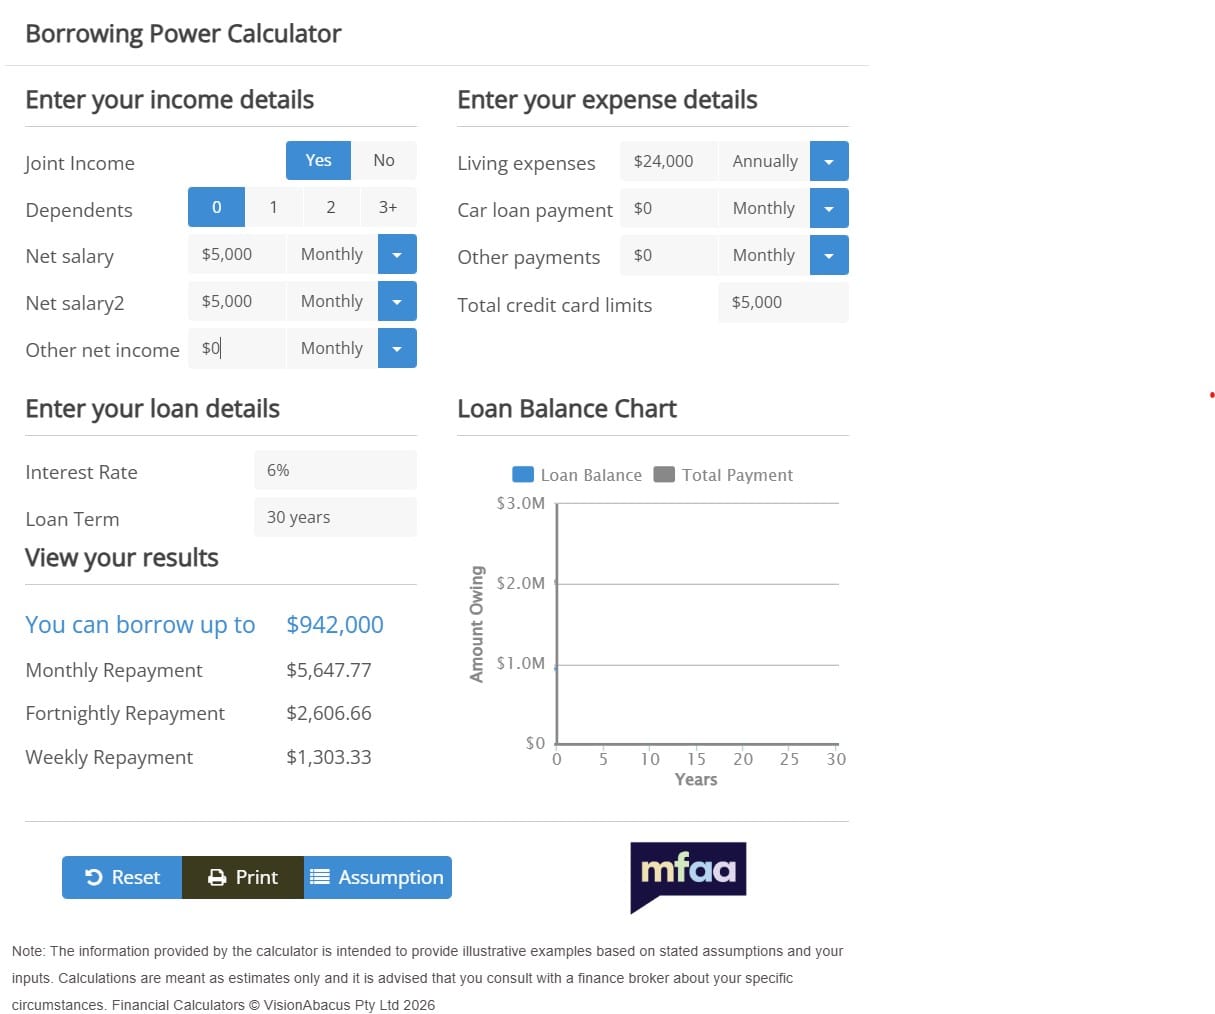
Borrowing Power Calculator
Estimate how much you may be able to borrow based on your income, expenses and existing commitments.
Home Loans for Medical Professionals: FAQs
LMI Waivers and Eligibility
It depends on the lender. Doctors, specialists and dentists are most commonly eligible, and some lenders include other registered health professionals. You’ll usually need current registration, and some lenders set a minimum income.
Some lenders do include nurses in their professional LMI waivers, so it’s worth comparing. Government schemes such as the 5% Deposit Scheme, and some lender discounts, may help you buy with a smaller deposit. Eligibility criteria apply.
Yes. Each lender sets its own maximum loan size and deposit level for professional LMI waivers, and these can differ by profession. We compare the current limits for you.
Income and Applications
Often, yes. Many lenders accept a current or signed future contract as evidence of ongoing income, especially within an accredited training pathway.
Many lenders count some or all of it, particularly if you have a consistent history. Some lenders shade it, so choosing the right lender can change how much you can borrow.
Usually, yes. Lenders generally assess ABN income like self-employed income, using tax returns or BAS. Some lenders accept a shorter trading history for medical professionals.
The information on this page is general in nature and does not take into account your objectives, financial situation or needs. Lending criteria, fees and charges apply. Consider whether it is appropriate for you and speak to us for advice specific to your situation. Eligibility criteria apply to government schemes.
Need Some Help?
Not sure where to start? That’s exactly what we’re here for. Drop us a message and we will get back to you within one business day with clear, honest advice tailored to your situation.