
Use this credit card calculator to understand how long it’ll take to repay your balance and how much interest you will pay.
Compare Your Repayment Options
This calculator will show you how long it’ll take you to repay your credit card debt if you were to make the minimum repayments. Compare this against how long it’d take (and how much interest you would pay) if you were to make higher repayments. We work with you to understand your debt and find a suitable strategy that will help you pay it back faster. Get in touch today to hear about your options.
How to use it: click Launch Calculator below, enter your details to see your estimate, then change the figures to compare different scenarios.
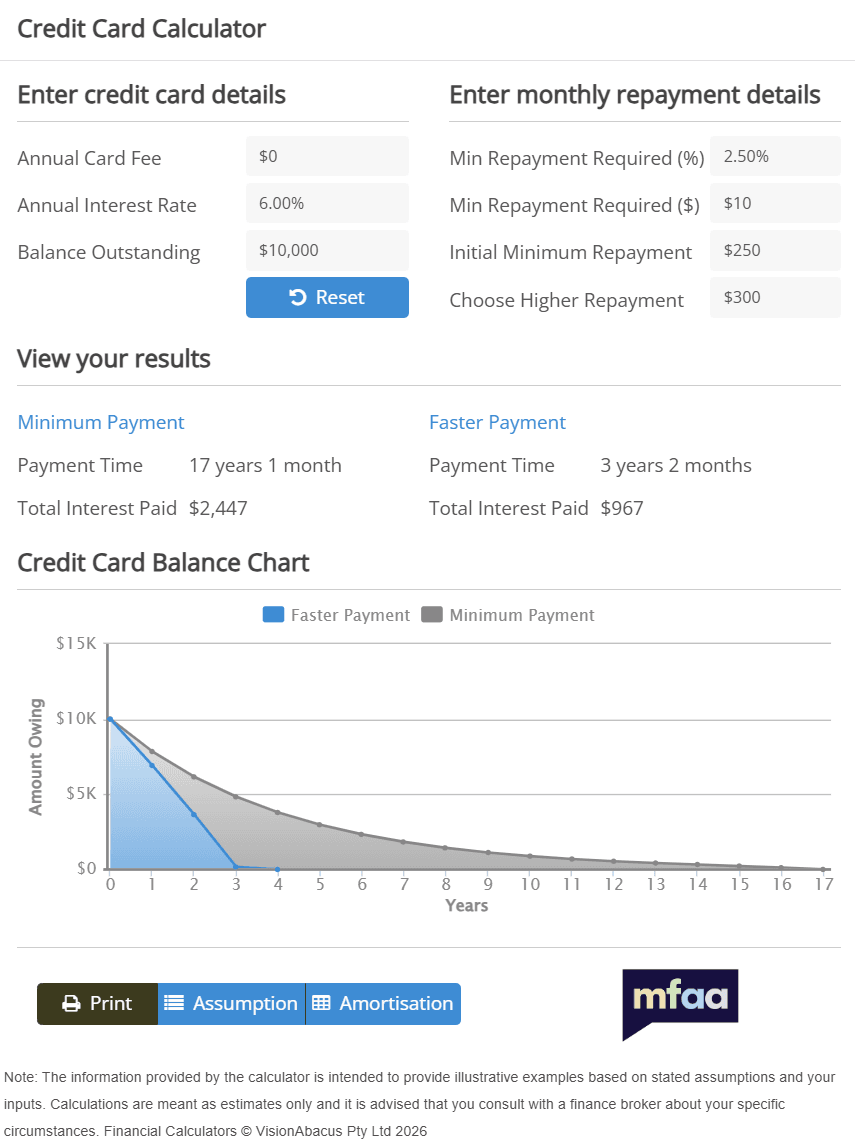
Credit Card Repayment Calculator
See how long paying off your card will take based on both minimum and extra repayments.
How to Use the Credit Card Calculator
The credit card calculator above shows how long it could take to pay off your balance and how much interest you might pay along the way. It compares paying only the minimum with paying a higher, fixed amount each month.
- Enter your current balance. If you have more than one card, run each card separately or add the balances together.
- Enter the card’s purchase interest rate, which appears on your statement.
- Enter the minimum repayment details and the amount you plan to pay each month.
- Then try higher repayments to see how much time and interest you could save.
The calculator assumes you stop using the card for new purchases. If you keep spending on it, the balance will take longer to clear.
How to Read Your Credit Card Repayment Results
Focus on two numbers: the time it takes to clear the card and the total interest. Minimum repayments keep the account in order, but they aren’t designed to clear the debt quickly. Because the minimum usually falls as the balance falls, paying only the minimum can stretch a modest balance over many years.
According to Moneysmart, citing Reserve Bank data, the average credit card interest rate is over 18%, and rates between cards can differ by more than 10%. So a lower rate, or a firm plan to clear the balance, can make a big difference.
Worked Example: Minimum vs Fixed Repayments
The figures below are hypothetical round numbers, for illustration only, not a current rate. They assume a $5,000 balance, an interest rate of 20% a year and no new spending.
- Minimum only (3% of the balance or $25, whichever is more): about 15 years to clear, with roughly $5,400 in interest.
- $200 a month: about 2 years and 9 months, with roughly $1,500 in interest.
- $400 a month: about 15 months, with roughly $650 in interest.
In other words, doubling a fixed repayment from $200 to $400 roughly halves the time and cuts the interest by more than half. Minimum repayment formulas differ between cards, so run your own figures through the credit card calculator.
How Credit Card Limits Affect Your Home Loan Borrowing Power
This is the part many people miss. When you apply for a home loan, many lenders look at your credit card limit, not your balance. In general, they assume the card could be fully drawn and include a monthly repayment on the whole limit, even if you clear the card every month.
For example, a card with a $20,000 limit and a zero balance can still reduce how much you can borrow. Consequently, reducing or closing cards you don’t need before you apply can help. Moneysmart notes that you don’t have to accept the full limit a card provider offers. Try our borrowing power calculator to see the difference a lower limit makes.
Ways to Pay Off Credit Card Debt Faster
- Pay more than the minimum, ideally a fixed amount by direct debit just after payday.
- Target the highest rate card first, or the smallest balance first if that keeps you motivated.
- Consider a balance transfer carefully: check the rate it reverts to, any fees, and stop new spending on the old card.
- Compare a fixed term personal loan.
- Read our guide to debt consolidation in Australia before rolling debts into your home loan, because spreading short-term debt over a long term can cost more interest overall.
If repayments are hard to manage, contact your card provider early or visit our financial difficulty and hardship hub.
Limitations of This Calculator
The credit card calculator assumes a constant interest rate and no new purchases, fees or interest-free periods. It doesn’t allow for cash advance rates, annual fees or balance transfer revert rates, so treat the results as a guide rather than an exact payoff date.
Local Help, Australia-Wide
Ingram Financial is a Sutherland Shire mortgage broker based in Bangor, NSW, and we also help clients across Australia by phone and video. If card debt is holding back a home purchase or refinance, we can look at your options across our home loan lenders.
Credit Card Calculator FAQs
It depends on the balance, rate and minimum formula, but it can take many years. Enter your figures in the credit card calculator to see your own estimate.
Clearing the balance helps your budget. However, many lenders assess the limit, so reducing or closing the limit usually has a bigger effect on borrowing power.
If you don’t need it, closing it or lowering the limit can help. Avoid applying for new credit just before a home loan.
Often, but not always. Compare the comparison rate, fees and term. A personal loan has a set end date, which can make it easier to clear the debt.
Get Help With Credit Card Debt
Want to clear card debt or understand how it affects a home loan? We can help you work out a plan. Call Shannon on 0402 283 480 or book a time that suits you. You’ll receive our Credit Guide, which explains how we’re paid, before we start working together.
The information on this page is general in nature and does not take into account your objectives, financial situation or needs. Lending criteria, fees and charges apply. Consider whether it is appropriate for you and speak to us for advice specific to your situation.
Need Some Help?
Not sure where to start? That’s exactly what we’re here for. Drop us a message and we will get back to you within one business day with clear, honest advice tailored to your situation.