
A honeymoon loan can help reduce your monthly repayments for a set term. Use this honeymoon rate calculator to compare your repayments with a standard variable loan.
How Much Would a Honeymoon Loan Save You?
If you’re eligible for a honeymoon loan you will benefit from lower monthly repayments for a set period of time before moving to the variable rate. Get in touch to see whether you qualify for a honeymoon loan.
How to use it: click Launch Calculator below, enter your details to see your estimate, then change the figures to compare different scenarios.
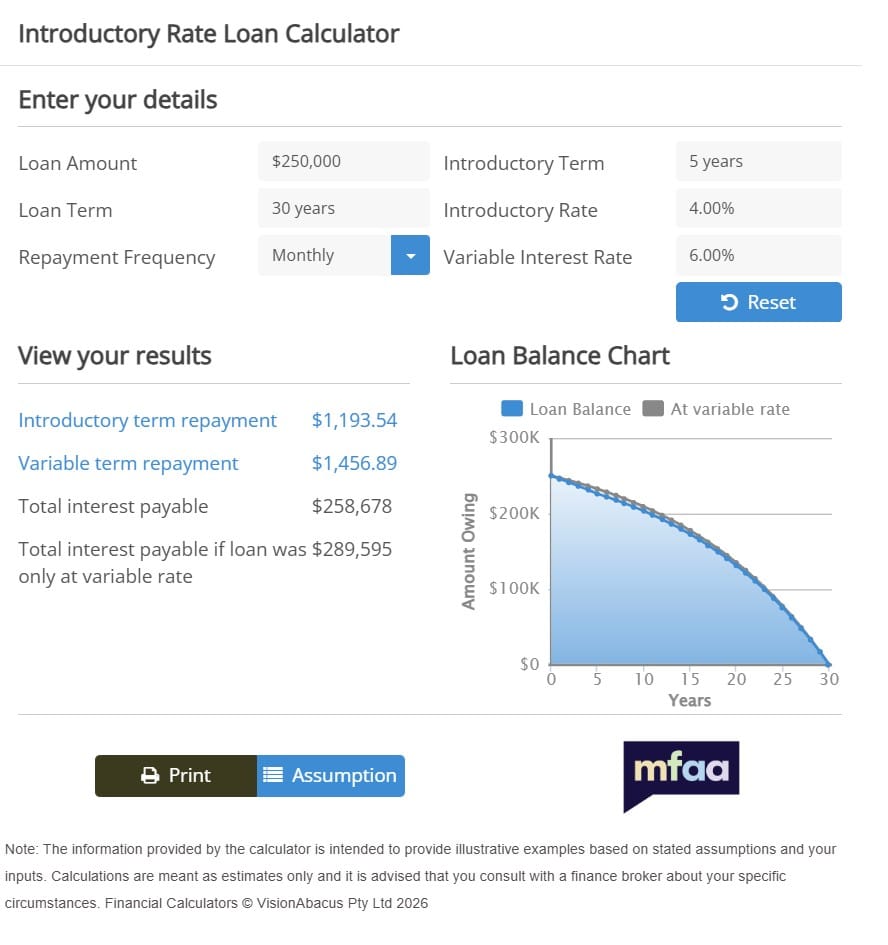
Honeymoon Loan Repayment Calculator
See what happens to your loan repayments once your introductory or honeymoon period ends.
What Is a Honeymoon Rate?
A honeymoon rate, also called an introductory rate, is a discounted interest rate that applies for a limited period at the start of a loan. When that period ends, the loan moves to the lender’s ongoing rate, known as the revert rate. Some introductory rates are variable, while others are fixed for the introductory period.
How to Use the Honeymoon Rate Calculator
- Enter the loan amount and loan term.
- Enter the introductory rate and how long it lasts.
- Enter the rate that applies afterwards (the revert rate).
- Compare the repayments during and after the honeymoon period, as well as the total interest.
It’s worth running the honeymoon rate calculator a few times with different revert rates, including a higher one, to test how comfortable you would be if rates move.
Worked Example: Repayments Before and After the Honeymoon
The figures below are hypothetical round numbers, for illustration only, not a current rate.
Say you borrow $600,000 over 30 years with an introductory rate of 5.99% for two years. Principal and interest repayments would be about $3,595 a month. After two years the balance is about $584,800, and the loan reverts to 6.99%. As a result, the repayment rises to about $3,970 a month over the remaining 28 years, an increase of roughly $375 a month.
By comparison, a loan at 6.99% from day one would cost about $3,990 a month. So the honeymoon period saves around $395 a month for two years, and then most of the benefit is gone. If the revert rate is higher than another loan’s ongoing rate, you could end up paying more over the life of the loan.
Revert Rate Risk
The revert rate usually matters more than the honeymoon rate, because you pay it for far longer. Before choosing, check what the ongoing rate is likely to be, whether fees apply if you switch or exit during the introductory period, and whether you could comfortably afford the higher repayment. Moneysmart suggests asking similar questions about any rate that ends and moves to a revert rate.
Look at the Comparison Rate, Not Just the Headline Rate
Moneysmart describes the comparison rate as a rate that includes the interest rate and most fees and charges, reduced to a single percentage. Because it also reflects the rate after the honeymoon period, it’s usually a better guide than the introductory rate on its own. Still, it doesn’t capture every cost, so read the loan’s key facts as well.
When the Honeymoon Ends: Your Options
Many borrowers review their loan as the introductory period ends. You could stay on the revert rate, ask your lender for a better rate, or refinance with another lender. Our guide to what happens when a fixed rate ends walks through the same choices. If you’re weighing up a fixed rate, our article on fixed vs variable home loans may help, and our loan comparison calculator lets you compare two loans side by side.
Limitations of the Honeymoon Rate Calculator
The calculator assumes rates stay the same after the introductory period, whereas variable rates can change at any time. It also leaves out fees, offset balances and extra repayments, so use it to compare options rather than to predict exact costs.
Local Help, Australia-Wide
Ingram Financial is a Sutherland Shire mortgage broker based in Bangor, NSW, and we also help clients across Australia by phone and video. We compare introductory and standard variable loans across our panel and explain the trade-offs. See our Home Loans page for the loan types we arrange.
Honeymoon Rate Calculator FAQs
It’s a home loan with a discounted introductory rate for a limited period. After that, the loan moves to the lender’s revert rate.
Your rate changes to the revert rate and your repayments usually rise. It’s a good time to review the loan and compare it with other options.
It can be, if the revert rate is competitive and you plan to keep the loan. A low introductory rate with a high revert rate may cost more over time, so compare the comparison rate.
Often you can, but check for exit or break costs first, especially if the introductory rate is fixed. Refinancing also involves a new application and assessment.
Compare Your Options With a Broker
Unsure whether an introductory rate suits you? We can compare it with other loans and show you the long-term cost. Call Shannon on 0402 283 480 or book a time that suits you. You’ll receive our Credit Guide, which explains how we’re paid, before we start working together.
The information on this page is general in nature and does not take into account your objectives, financial situation or needs. Lending criteria, fees and charges apply. Consider whether it is appropriate for you and speak to us for advice specific to your situation.
Need Some Help?
Not sure where to start? That’s exactly what we’re here for. Drop us a message and we will get back to you within one business day with clear, honest advice tailored to your situation.