
Use this loan repayment calculator to understand how much your home loan repayments might be.
How Much Will My Repayments Be?
This is one of the most common questions asked by our clients. This calculator will help give you an idea but there are a number of factors that determine what they will be (e.g. which lender you choose, what rate type you opt for and much more). We can help you understand your options, so give us a call to chat through the numbers in more detail.
How to use it: click Launch Calculator below, enter your details to see your estimate, then change the figures to compare different scenarios.
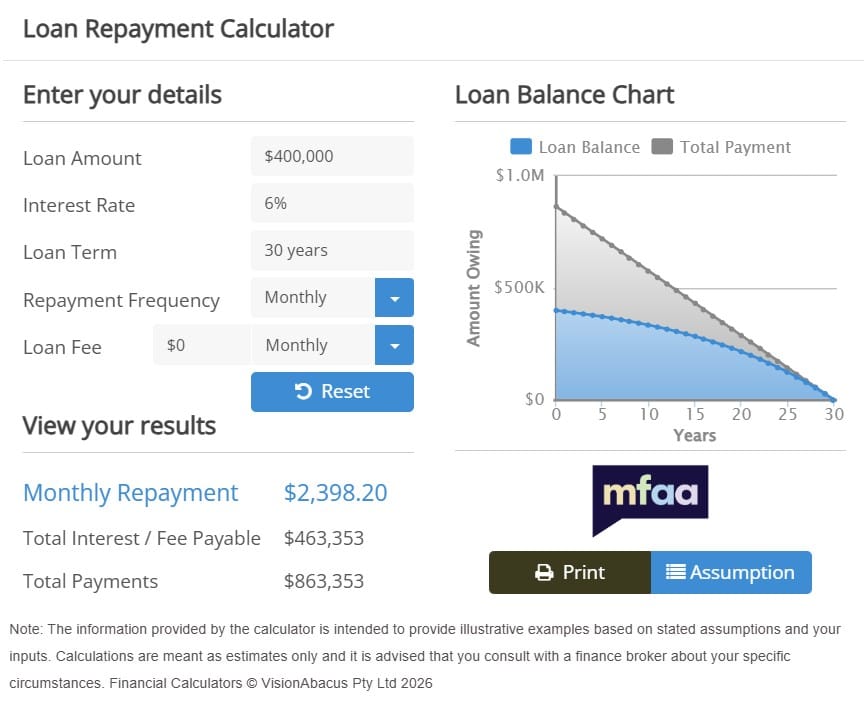
Loan Repayment Calculator
Easily see your repayments based on a specified loan amount, interest rate and term
How to Use the Loan Repayment Calculator
The loan repayment calculator above gives you a quick estimate of what a home loan could cost each month, fortnight or week. To get a useful result, enter:
- the amount you plan to borrow
- an interest rate to test (try a higher one too, as a buffer)
- the loan term in years (many home loans run for 30 years)
- how often you want to make repayments
The results show your estimated repayment plus the total interest over the life of the loan. Treat them as a guide rather than a quote.
Principal and Interest vs Interest Only
With a principal and interest loan, each repayment covers the interest charged plus part of the loan balance, so your debt falls over time. With an interest-only loan, you pay just the interest for an agreed period, so the balance does not reduce during that time.
Interest-only repayments are lower at first. However, when the interest-only period ends, repayments rise because you then repay the whole balance over a shorter remaining term. As a result, you usually pay more interest overall. Moneysmart explains the trade-offs in its guide to interest-only home loans.
How Repayment Frequency and Loan Term Change the Cost
Frequency. Paying fortnightly can help if your pay arrives fortnightly. In addition, if you pay half of the monthly amount every fortnight, you make 26 half payments a year. That works out to about one extra monthly repayment each year, and the extra goes straight off the principal.
Loan term. A longer term lowers each repayment but increases total interest, because you borrow the money for longer. On the other hand, a shorter term costs more each month but saves interest. Many borrowers therefore choose a longer term and make extra repayments when they can.
Worked Example: One Loan, Three Repayment Choices
For illustration only, not a current rate. The figures below use a hypothetical $600,000 loan at 6.50% p.a. and ignore fees.
- Principal and interest over 30 years, paid monthly: about $3,792 a month, with total interest of roughly $765,000.
- Interest only for five years, then principal and interest over the remaining 25 years: about $3,250 a month at first, then rising to about $4,051 a month. Total interest comes to roughly $810,000, which is about $45,000 more.
- Half the monthly repayment (about $1,896) paid every fortnight: the loan could be repaid roughly six years sooner, with total interest of around $589,000.
Try the same scenarios in the loan repayment calculator with your own numbers.
Limitations to Keep in Mind
Any calculator assumes the rate stays the same for the whole term, which rarely happens in practice. After several rate rises in 2026, many borrowers have seen their repayments change more than once. The calculator also leaves out fees, lenders mortgage insurance and your borrowing capacity. Lenders also test affordability at a higher rate than the one you pay.
Related Calculators and Guides
- Extra mortgage repayments calculator
- Mortgage offset calculator
- Borrowing power calculator
- Refinancing
- Moneysmart mortgage calculator
Ingram Financial is a mortgage and finance broker based in Bangor, NSW. We help borrowers across the Sutherland Shire, and we also work with clients right around Australia by phone and video.
Loan Repayment Calculator FAQs
No. It is an estimate based on the figures you enter. Your actual repayment depends on the lender, the rate you are offered, the loan features and any fees.
It often makes sense to match your pay cycle. Paying half the monthly amount each fortnight can also reduce interest over time, because it adds up to about one extra monthly repayment a year.
Some investors, and some borrowers with a short-term cash flow need, choose interest only for a period. It lowers repayments at first but usually costs more overall, so it is worth talking through with a broker first.
Talk Through Your Numbers
Want a second opinion on your repayments, or wondering whether a different loan could cost less? Book a free chat and we will compare options from our lender panel.
The information on this page is general in nature and does not take into account your objectives, financial situation or needs. Lending criteria, fees and charges apply. Consider whether it is appropriate for you and speak to us for advice specific to your situation.
Need Some Help?
Not sure where to start? That’s exactly what we’re here for. Drop us a message and we will get back to you within one business day with clear, honest advice tailored to your situation.