
Buying your first home is a major milestone, but navigating home loans, deposits, and government schemes can quickly become overwhelming.
At Ingram Financial, we help first home buyers across Australia secure the right home loan with confidence. Whether you’re purchasing in Sydney, regional NSW, or interstate, we guide you from pre-approval through to settlement.
Taking the headaches out of first home buyer home loans
Australia-Wide Mortgage Broker Support
We work with first home buyers across Australia, providing expert guidance regardless of location.
While we’re based in the Sutherland Shire in Sydney, our clients come from all across Australia, from regional NSW and Queensland to Victoria and Western Australia. With phone, video, and digital applications, the entire process can be handled remotely, without needing to visit a branch or office.
How Much Can You Borrow as a First Home Buyer?
Lenders look at much more than your income when they work out your borrowing capacity. They use what’s known as a serviceability calculation, which looks at your gross income, existing debts, living expenses and the size of your deposit. Based on these, they decide the maximum loan amount they’re comfortable lending you.
In addition, most lenders apply a “stress test” to check whether you could still afford repayments if interest rates rose by 3% above the loan rate. As a result, your actual borrowing limit is often lower than you might expect when you run the numbers yourself.
What Affects Your Borrowing Power
Common factors include your employment type (PAYG or self-employed), whether you have HECS/HELP debt, any existing car loans or credit cards, and the number of dependants in your household.
That’s why, at Ingram Financial, we assess your full financial picture before approaching any lender. This way, we match you with lenders whose policies suit your situation, and help you maximise your borrowing power without overextending.
To get started, use our calculator below for an approximate estimate of your borrowing power.
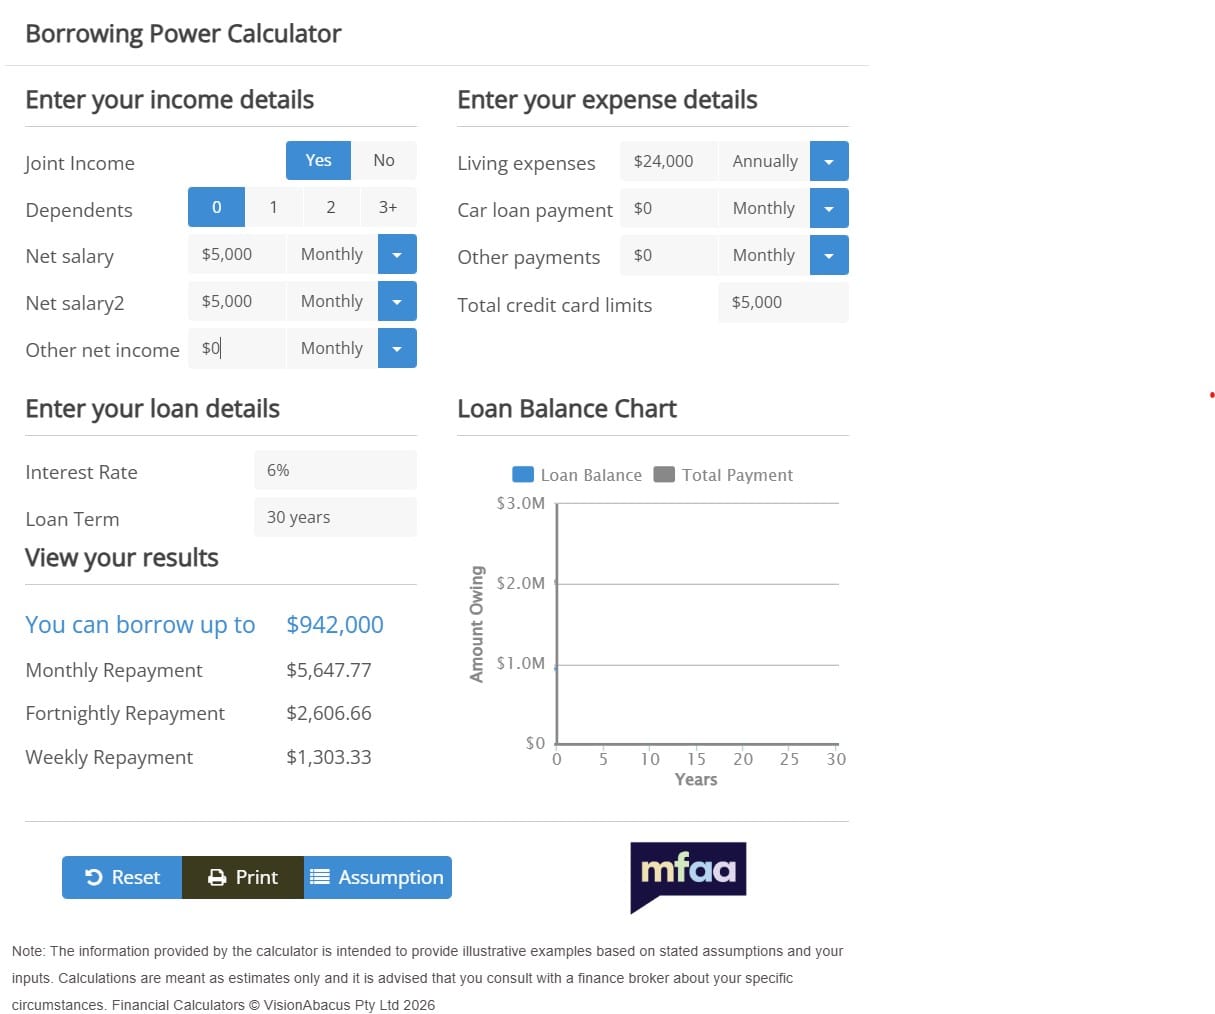
Borrowing Power Calculator
Estimate how much you may be able to borrow based on your income, expenses and existing commitments.
First Home Buyer Deposit Options
Putting down 20% has long been considered the standard, because it means you avoid Lenders Mortgage Insurance (LMI). In reality, however, most first home buyers get into the market with far less saved.
Lenders Mortgage Insurance (LMI)
LMI is a one-off insurance premium that you pay, but it protects the lender if you can’t keep up your repayments. Depending on how much you borrow and the size of your deposit, it can add anywhere from $8,000 to $30,000+ to your upfront costs. Fortunately, there are several ways to reduce or avoid this cost altogether.
Buying With a 5% Deposit
If you’ve saved a 5% deposit, you might qualify for the Australian Government 5% Deposit Scheme (formerly the First Home Guarantee). It lets eligible buyers purchase with only 5% upfront, because the government guarantees up to 15% of the property value, so you don’t pay LMI. Since 1 October 2025 there are no income caps and no limit on places, although price caps apply (in NSW, $1,500,000 in Sydney and the major regional centres and $800,000 elsewhere). Single parents and single legal guardians can buy with a 2% deposit under the same scheme, and the Help to Buy shared equity scheme also starts from a 2% deposit.
Buying With Help From Family
Another option is a guarantor loan, where a relative (usually a parent) offers equity in their own home as extra security for the lender. Depending on your circumstances, this could even let you buy with no deposit at all, and without paying LMI.
Either way, we’ll help you work out which pathway best suits your circumstances and where you currently stand with your savings.
Government Grants & Schemes Available in Australia
Depending on the state or territory you’re purchasing in, you may be eligible for a range of government grants and concessions. These can make a significant difference to the upfront costs of buying your first home.
| State/Territory | Grant Name | Amount | Conditions |
|---|---|---|---|
| NSW | First Home Owner (New Homes) Grant | $10,000 | New or substantially renovated homes only. Purchase price up to $600,000, or up to $750,000 for a house and land package or building contract |
| VIC | First Home Owner Grant | $10,000 | New homes only, valued up to $750,000 |
| QLD | First Home Owner Grant | $30,000 | New homes only, valued under $750,000 (contracts signed on or after 20 November 2023) |
| WA | First Home Owner Grant | $10,000 | New or substantially renovated homes only. Value cap $800,000 south of the 26th parallel (includes Perth) or $1,000,000 north of it, for transactions from 7 May 2026 |
| SA | First Home Owner Grant | Up to $15,000 | New homes only. No property value cap for contracts signed on or after 6 June 2024 |
| TAS | First Home Owner Grant | $20,000 | New homes only, for transactions between 1 July 2026 and 30 June 2027. No property value cap |
| ACT | Home Buyer Concession Scheme | Full stamp duty exemption | No income threshold or property value limit from 1 July 2026. Buyers must not have owned property in the previous 5 years |
| NT | HomeGrown Territory Grant | $50,000 | New homes only (buy or build), contracts signed between 1 October 2024 and 30 September 2027. No price cap |
Figures checked against official state and federal government websites on 30 September 2026. Grants and caps change often, so we’ll confirm your eligibility before you apply.
Federal Government Schemes
In addition to state-based grants, the Federal Government offers three key programs:
- Australian Government 5% Deposit Scheme (formerly the First Home Guarantee): eligible first home buyers can purchase with as little as a 5% deposit, and single parents or single legal guardians with 2%. The government guarantees up to 15% of the property value, which means you pay no LMI. There are no income caps and unlimited places, but property price caps apply by location.
- First Home Super Saver Scheme (FHSS): you make voluntary contributions into your superannuation fund, then withdraw those contributions (plus associated earnings) to use as a home deposit. Up to $15,000 of contributions count in any one financial year, and you can withdraw up to $50,000 of contributions per person, which makes it a tax-effective way to save.
- Help to Buy: a shared equity scheme where the Australian Government contributes up to 30% of the price of an existing home or 40% of a new home, so you can buy with a 2% deposit and a smaller loan. Income caps ($103,000 for singles, $165,000 for couples and single parents) and price caps apply, and the government’s share is repaid when you sell or when you can afford to buy it back. See firsthomebuyers.gov.au for details.
Stamp Duty Concessions
Most states also offer full or partial stamp duty exemptions for first home buyers. In NSW, for example, first home buyers purchasing a new or existing home valued up to $800,000 pay no transfer duty at all, and a concessional rate applies between $800,000 and $1,000,000 (vacant land: exempt up to $350,000, concession up to $450,000). See Revenue NSW for the current thresholds.
Keep in mind that eligibility conditions vary by state and scheme, and the rules change regularly. We keep up to date with every scheme and manage the application process on your behalf.
Buying Your First Home in the Sutherland Shire
The Shire is a popular place to put down roots, and plenty of first home buyers want to stay close to family, beaches and bushland. With the right plan, getting into the local market is more achievable than many people think.
Where First Home Buyers Are Buying
- Units and townhouses near transport. Apartments around Sutherland and Kirrawee, Miranda and Caringbah and Cronulla are a common first step into the Shire.
- Houses in the upper Shire. Suburbs like Engadine and Heathcote and Menai and its neighbours are often a more accessible way to buy a house in the area.
Help That Can Make a Difference
- Government schemes. Eligible buyers may be able to buy with a 5% deposit through the Australian Government 5% Deposit Scheme, and NSW offers stamp duty exemptions and concessions below certain price thresholds.
- Family help. A family guarantee or a gifted deposit can help you buy sooner. Both have pros and cons for everyone involved, so get advice before committing.
- Pre-approval before auction. Auctions are common across the Shire, and auction purchases are unconditional, so have your finance sorted before you bid.
Buying in the Shire? See our Sutherland Shire mortgage broker page, or book a free first home chat.
Why Use a Mortgage Broker?
Working with a mortgage broker gives you access to more options and better guidance than going directly to a bank.
We provide:
- Access to a wide panel of lenders
- Tailored loan recommendations
- Support with paperwork and approvals
- Ongoing reviews after settlement
We focus on finding the right loan for your situation, not just what one lender can offer.
Why First Home Buyers Trust Ingram Financial
Ingram Financial is a Sutherland Shire-based mortgage broking business helping Australians buy their first home with confidence. Led by Shannon Ingram, a fully accredited mortgage broker authorised under LMG Broker Services, we work with a broad panel of lenders (from the major banks to specialist non-bank lenders) to find the right loan for your situation.
Unlike going directly to a bank, where you’re limited to that lender’s products and credit policies, working with a broker gives you access to dozens of lenders simultaneously. We do the comparison work for you, handle the paperwork, and advocate on your behalf throughout the entire process, from pre-approval through to settlement and beyond.
Our services are at no cost to you. We are paid by the lender when your loan settles, and we are legally required to act in your best interests under the Best Interests Duty.
Our First Home Buyer Process
1. Initial Consultation
We understand your goals and financial position
2. Borrowing Assessment
We calculate your budget and borrowing power
3. Pre-Approval
Get clarity before you start house hunting
4. Property Purchase Support
Guidance through contracts and negotiations
5. Loan Approval & Settlement
We manage the process through to completion
First Home Buyer FAQs
Deposits, Costs and Eligibility
Yes. Through the Australian Government’s 5% Deposit Scheme (formerly the First Home Guarantee), eligible buyers can purchase with as little as a 5% deposit without paying Lenders Mortgage Insurance (LMI). The government guarantees up to 15% of the property value. Since October 2025 there are no income caps and no limit on places, although property price caps apply. Outside of this scheme, some lenders will accept a 5% deposit with LMI payable on top.
These may include stamp duty (if applicable), legal fees, inspections, and lender costs. There are no costs to utilise Ingram Financial’s services as we are paid by the lenders when your loan settles.
There’s no universal minimum, as each lender uses different credit scoring models and policies. Generally, a credit score above 600 (on a scale of 0–1,200) is considered acceptable by most mainstream lenders. However, some specialist lenders will consider applicants with lower scores. We can run a credit check as part of your initial assessment and advise you on the best path forward.
Yes. Parents can help with a gifted deposit, or by offering equity in their own home as security through a family guarantee. A guarantee can help you avoid LMI, but it puts some of their equity at risk. Everyone involved should get independent advice.
Getting Approved
No. We work with clients across Australia using phone, email, and video.
Once we have your documents, we can usually submit your application within a day. Lender turnaround then varies: some lenders respond the same day, some take a few days and a handful take over a week. Timing also depends on the time of year and the complexity of your situation.
Pre-approval (also called conditional approval) is an assessment by the lender of your financial position that gives you a borrowing limit to shop with. It’s based on the information you provide and is typically valid for 90 days. Full (unconditional) approval comes after you’ve made an offer on a specific property and the lender has assessed both your finances and the property itself. Pre-approval is not a guarantee of full approval but is a strong indicator of your borrowing position.
Buying in the Sutherland Shire
It depends on your income, deposit and the type of property you’re after. Many first home buyers start with a unit or townhouse, or look at the upper Shire for houses. We’ll work out your real borrowing power and which schemes you’re eligible for, so you know exactly what’s realistic.
Why First Home Buyers Choose Ingram Financial
- Clear, straightforward advice
- Support from start to finish
- Access to multiple lenders
- Help with grants and applications
- Long-term loan support
Free Guide: 4 Steps to Doing Your First Home Loan Right
Our free ebook explains everything you need to know about your first home loan in Australia and what to consider before applying for a loan. Learn how lenders assess applications, compare finance options, and avoid common mistakes that can cost borrowers thousands over the life of a loan.
Download your free copy below.
Ready to Buy Your First Home?
Wherever you are in Australia, we’re here to help you take the next step.
The information on this page is general in nature and does not take into account your objectives, financial situation or needs. Lending criteria, fees and charges apply. Consider whether it is appropriate for you and speak to us for advice specific to your situation.
Need Some Help?
Not sure where to start? That’s exactly what we’re here for. Drop us a message and we will get back to you within one business day with clear, honest advice tailored to your situation.