
Use the balloon payment calculator to understand the impact that a balloon payment will have on your monthly loan repayments and the total amount of interest you’ll be required to pay.
Impact of Balloon Payments
Use our balloon payment calculator to estimate the lump sum payable at the end of your loan term. This helps you understand your future financial commitment and structure your finance with confidence.
Whether you’re considering a car loan, business loan, or asset finance, this calculator helps you plan repayments and avoid surprises at the end of your loan term.
Enter your loan details including the residual (balloon) amount to estimate:
- Your regular repayment structure
- Total cost of the loan over time
How to use it: click Launch Calculator below, enter your details to see your estimate, then change the figures to compare different scenarios.
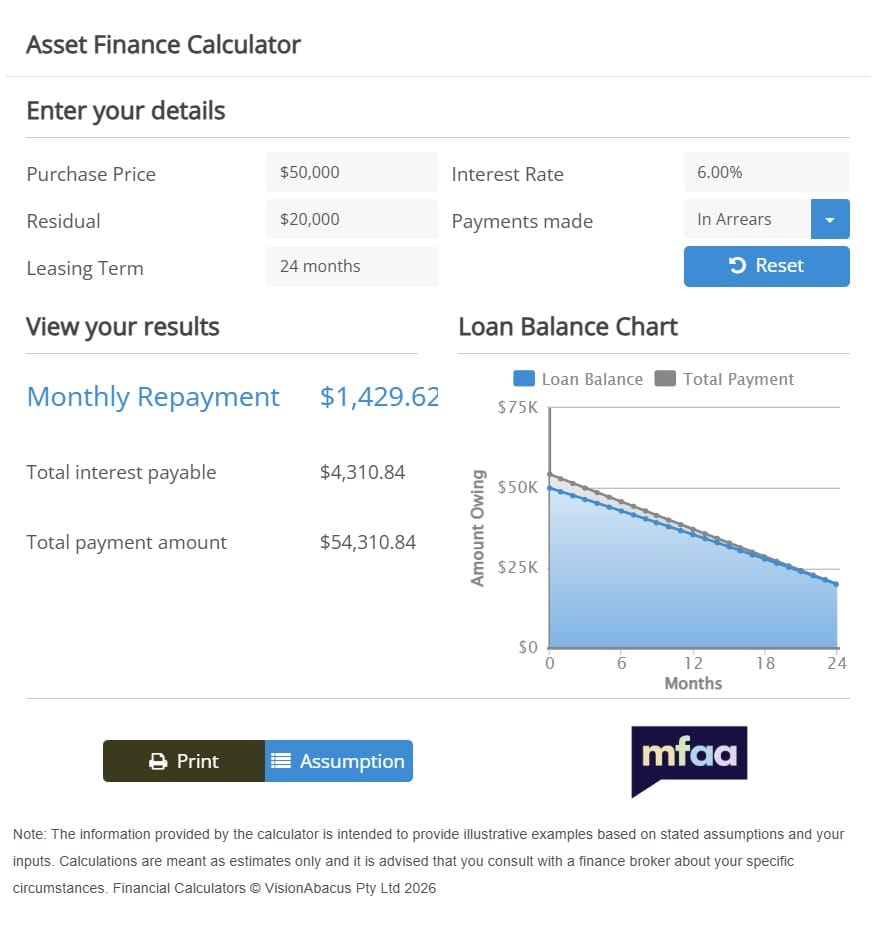
Balloon Repayment Calculator
Easily see your repayments based on a specified loan amount, interest rate and term and the impact that a residual or balloon payment can have on them
Found a repayment that works for you? As a local car loan broker, we can compare car finance with and without a balloon across our lender panel and get you pre-approved before you shop.
What Is a Balloon Payment?
A balloon payment is a larger lump sum due at the end of a loan term. It reduces your monthly repayments during the loan but requires careful planning for the final payout.
This structure is commonly used for:
- Car loans
- Equipment finance
- Business asset loans
- Some commercial lending products
How Balloon Payments Work
With a balloon loan:
- You make lower regular repayments during the loan term
- A larger final payment is due at the end
- You may refinance, pay out, or trade in the asset
This structure can improve cash flow but requires a clear exit strategy.
Benefits of Using a Balloon Loan Structure
- Lower monthly repayments
- Improved short-term cash flow
- Greater flexibility for business or personal finance
- Access to higher-value assets sooner
Things to Consider
Before choosing a balloon structure, consider:
- How you will repay the final lump sum
- Whether refinancing will be required
- The impact on total interest paid
- Your future income stability
Choosing a Percentage in the Balloon Payment Calculator
Most people using a balloon payment calculator want to know what percentage to choose. Many lenders set a maximum balloon based on the loan term and the type of vehicle, and that maximum usually gets smaller as the term gets longer.
A sensible starting point is to estimate what the car may be worth at the end of the term, then choose a balloon comfortably below that figure. That way, if you sell or trade in the car, the sale is more likely to cover the balloon.
What Happens at the End of the Term
- Pay it out from savings and own the car outright.
- Refinance the balloon into a new loan, subject to lender approval. This adds more interest, so compare the cost first.
- Sell or trade in the car and use the proceeds to clear the balloon, then finance your next vehicle.
Comparing the Total Cost With and Without a Balloon
For illustration only, not a current rate. On a hypothetical $50,000 car loan over five years at 8.00% p.a., ignoring fees, no balloon means repayments of about $1,014 a month and about $10,830 in interest. With a 30% balloon ($15,000), repayments drop to about $810 a month. However, interest rises to about $13,580, and you still owe $15,000 at the end.
In other words, the balloon frees up about $204 a month but costs around $2,750 more in interest. Our car loan calculator covers loans without a balloon.
Balloon Payments for Business Owners and ABN Holders
Business owners often use a balloon with a chattel mortgage or other asset finance to keep cash flow steady. The tax treatment depends on how the vehicle is used and financed, and the ATO explains motor vehicle expenses for businesses. Speak to your accountant or tax adviser about tax.
Based in Bangor in the Sutherland Shire, we also help clients across Australia by phone and video.
Need Help Structuring Your Loan?
Balloon payments can be powerful when structured correctly. We can help you compare lenders and design a finance structure that suits your goals.
Buying a car, ute or work vehicle, or financing business equipment? We compare lenders for car loans and asset finance, including balloon structures, and explain your options in plain English.
Car Loan Frequently Asked Questions
You may be able to refinance the remaining amount or restructure the loan, subject to lender approval.
Yes, but this usually increases your regular repayments.
It depends on your cash flow, financial goals, and how you plan to exit the loan.
More Balloon Payment Questions
There is no single right answer. Many people choose a balloon below the car’s likely value at the end of the term, so selling or trading in the car can cover it.
The information on this page is general in nature and does not take into account your objectives, financial situation or needs. Lending criteria, fees and charges apply. Consider whether it is appropriate for you and speak to us for advice specific to your situation. Speak to your accountant or tax adviser about tax.
Need Some Help?
Not sure where to start? That’s exactly what we’re here for. Drop us a message and we will get back to you within one business day with clear, honest advice tailored to your situation.