
Please note: this article was published in August 2026 and updated on 1 October 2026 to reflect the Reserve Bank’s September rate rise and that the negative gearing and capital gains tax changes are now law. Interest rates and lender policies can change quickly, so contact us for the latest information.
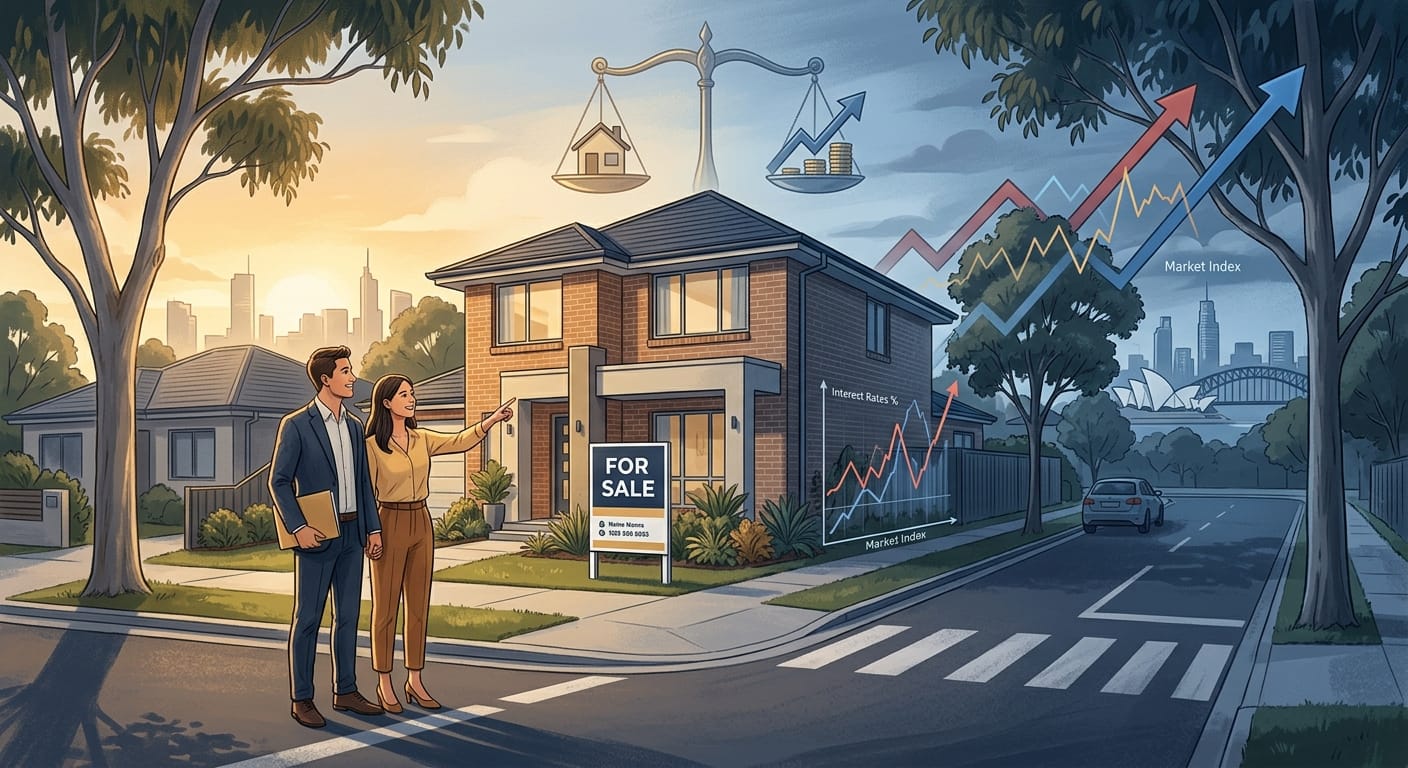
You’ve probably noticed the headlines. Property prices are slipping in most capital cities, the Reserve Bank has lifted rates four times this year, and the tax rules for property investors have been rewritten. If you’re weighing up whether to buy property in Australia or hold off, the timing feels unusually complicated right now.
The honest answer is that “now” isn’t universally good or bad. It depends heavily on who you are. A first home buyer and a seasoned investor are looking at two very different markets right now, even though they’re reading the same news. This post breaks down what’s actually changed and what it means for each group.
What’s Actually Happening in the Market
Three things are colliding at once, and it’s worth separating them out.
Interest rates have moved higher. The RBA lifted the cash rate in February, March and May 2026, held in June and August, then raised it again on 29 September to 4.60%. That’s four rises this year, reversing the three cuts of 2025, and the cash rate is now at its highest level in about 15 years. In its September statement, the RBA said inflation is still too high and it will increase the cash rate further if needed. Higher rates push up borrowing costs and cool buyer demand.
The Budget’s property tax changes are now law. Announced on 12 May 2026 and passed as the Treasury Laws Amendment (Tax Reform No. 1) Act 2026, they change the numbers for investors in two ways. First, for established residential properties bought after Budget night, negative gearing losses will no longer offset your other income, like your salary, from 1 July 2027. New builds can still be negatively geared, and existing investments are grandfathered. Second, for gains that accrue after 1 July 2027, the 50% capital gains tax discount is replaced by indexation of your cost base in line with inflation (CPI), plus a 30% minimum tax on the real gain. Gains made before 1 July 2027 keep the 50% discount, and investors in new builds can choose either method. The intent is to steer investment toward new housing supply. We explain the detail in our guide to the negative gearing changes from 2027.
Prices and lending have cooled. The RBA’s September statement noted that housing prices have fallen in most capital cities and new housing loans have declined noticeably. ABS lending figures for the June quarter 2026 tell the same story: the number of new investor loans fell 8.6% and new owner-occupier loans fell 3.3%. Economists differ on how far and how long prices will soften, and with the RBA signalling it may lift rates again, those forecasts can change quickly.
The upshot: after a strong run in 2025, the market has clearly cooled. The effects are landing unevenly across cities, suburbs and property types, so national headlines only tell you part of the story for the street you’re looking in.
For First Home Buyers: A Rare Window Is Opening
If you’ve been trying to buy for the past couple of years, you’ll know how brutal it’s felt competing against investors at auction. That competition is now easing, and that can change your position more than the price falls themselves do.
Less investor competition works in your favour. With new investor lending already down 8.6% in the June quarter, and the tax changes making established homes less attractive to new investors, there may be fewer investors bidding against you for the exact three-bedroom house you actually want to live in, even in suburbs where headline prices haven’t dropped much.
Softer prices buy you time. When the market is cooling rather than sprinting, you’re not racing to buy before it runs away from you. You can take a few extra weeks to get finance sorted properly, inspect more properties, and negotiate rather than panic-bid.
Rates cut both ways for you. Higher interest rates mean your borrowing capacity is lower than it would have been at the start of the year (we explain why in why has my borrowing capacity reduced?), so it’s worth getting a proper assessment of what you can actually borrow before you start looking. Pre-approvals generally last about three months, so if yours was issued before the September rise, it’s worth checking it still stacks up. This is exactly where talking to a broker earns its keep: we can model your capacity against current rates and any government scheme you might be eligible for, such as the 5% Deposit Scheme, which has no income caps and a $1.5 million price cap in Sydney and NSW regional centres. That way you’re shopping with a realistic number in mind.
Don’t wait for the “perfect” bottom. Trying to time the exact low point of a property cycle is a losing game even for professional investors. If a property suits your life and the numbers work at today’s rates, with some room for further rises, a softer market with less competition may be a better entry point than waiting and hoping prices fall further while rates stay elevated. Just make sure the repayments are comfortable, not merely possible.
For Investors: The Playbook Has Changed, Not Ended
If you’re an existing investor, the grandfathering provisions mean your current negative gearing arrangements aren’t retrospectively affected. It’s new purchases where the calculus has shifted.
New builds now have a clear tax advantage over buying an established property in Australia. Because negative gearing on new investment property has been preserved while established property bought after Budget night loses that offset against other income, the numbers increasingly favour new dwellings, off-the-plan purchases, and knockdown-rebuild strategies over buying an existing house to rent out.
Your after-tax return calculation needs an update. Run your numbers again rather than relying on assumptions from a year ago. The combination of a 4.60% cash rate and the loss of the income offset on established properties can meaningfully change whether a deal still stacks up. This is worth doing with your broker and accountant together before you commit to anything.
Softer prices can mean better entry points, if your fundamentals are sound. A cooling market with less competition can work in an investor’s favour too, particularly for new-build purchases where the tax settings are now more favourable. The catch is financing: with rates higher than at the start of the year, you need to stress-test serviceability more carefully than you might have previously.
Factor the CGT changes into your exit strategy. For gains accruing after 1 July 2027, indexation means you’re only taxed on the gain above inflation, but a 30% minimum tax applies to that real gain. Whether you end up paying more or less than under the old 50% discount depends on your income, how long you hold, and how much of the gain is inflation. Investors in new builds can choose whichever method works better for them. Ask your accountant to model your likely position before you buy, rather than as an afterthought when you sell.
Look past the headlines on location. With the RBA noting falls in most capital cities, and conditions varying between and within cities, local fundamentals such as rental demand, vacancy rates and new supply matter more than national averages. A purely Sydney or Melbourne-focused strategy isn’t automatically right or wrong, but it’s worth widening the lens.
So, Is Now a Good Time to Buy?
For first home buyers, current conditions (softer prices, easing investor competition, and time to breathe rather than panic-bid) are more favourable than they’ve been for some time, provided you can comfortably service a loan at today’s rates with a buffer for further rises.
For investors, the opportunity hasn’t disappeared, but the rules of the game have changed. New builds are now the more tax-effective play, and the numbers need re-running before you commit.
In both cases, the right move on whether to buy property in Australia or not depends on your borrowing capacity, your goals, and how the new tax settings actually affect your specific situation, not on trying to guess where the market bottoms out. That’s exactly the kind of thing worth talking through before you make an offer.
If you want to know what you can actually borrow under the current rates and rules, get in touch with Ingram Financial and we’ll run the numbers with you.
The information in this article is general in nature and does not take into account your objectives, financial situation or needs. Lending criteria, fees and charges apply. Consider whether it is appropriate for you and speak to us for advice specific to your situation.
Need Some Help?
Not sure where to start? That’s exactly what we’re here for. Drop us a message and we will get back to you within one business day with clear, honest advice tailored to your situation.